The near‑term market is focused on oil flows and inflation, but this conflict is likely to leave a lasting economic, geopolitical, and investment impact.
1. Higher prices and more persistent inflation
Repeated supply shocks reinforce price pressures
Energy costs feed through to transport, food, and manufacturing
Inflation expectations risk becoming less anchored, making central banks’ jobs harder
“Having another hit to supply and a boost to inflation so soon after the last one runs the risk of a further boost to inflation expectations, and a loss of faith in central banks,” said AMP Chief Economist & Head of Investment Strategy Shane Oliver.
Why it matters:
Inflation may prove harder to bring back to target, keeping interest rates higher for longer.
2. Elevated geopolitical risk
The conflict reinforces a shift from a US‑led unipolar world to a more fragmented, multipolar one
Global rules‑based systems are weakened as power politics take precedence.
Regional conflicts increasingly carry global economic consequences
“It’s hard to see this not being interpreted by other powerful countries as a green light to do whatever they want in their region and beyond,” said Oliver.
Why it matters:
Higher geopolitical risk raises uncertainty for trade, investment, and financial markets.
3. Renewed global terrorism risk
A prolonged Middle East conflict raises the risk of radicalisation and retaliatory attacks
Markets can typically look through isolated events, but broader or sustained incidents would matter more
Why it matters:
Increased uncertainty weighs on confidence, travel, and investment.
4. Higher defence spending globally
Rising geopolitical risk almost always leads to increased military budgets
Pressure grows on US allies, including Australia, to spend more on defence
Why it matters:
More defence spending can crowd out productivity‑enhancing investment and add to public debt.
5. More investment in oil and gas infrastructure
The weaponisation of the Strait of Hormuz has highlighted our global energy vulnerability
Countries are incentivised to build alternative routes, boost reserves, and increase domestic production
Why it matters:
Energy security, even if it has to be achieved through fossil fuels, becomes a strategic priority, even as the transition continues.
6. Stronger push toward renewables and nuclear energy
Renewables and nuclear are not exposed to Middle East shipping routes or geopolitics
Energy independence becomes as important as emissions reduction
“The sun, the wind and nuclear energy do not depend on volatile politics in the Middle East,” said Oliver.
Why it matters:
Structural support for clean energy investment strengthens over time.
7. More pressure to onshore supply chains
Strategic industries (energy refining, fertilisers, metals, defence inputs) face renewed pressure to localise
Reinforces deglobalisation trends that began with the pandemic
Why it matters:
Onshoring reduces domestic vulnerabilities in case of global supply chain disruptions, but often increases costs and inflation pressures.
8. Reinforcement of a more crisis‑prone world
This conflict adds to a growing list of global shocks over the past two decades
Crises are becoming more frequent and less tied to traditional economic cycles
“The Iran war is now the fifth major global shock in the last 20 years,” said Oliver.
Why it matters:
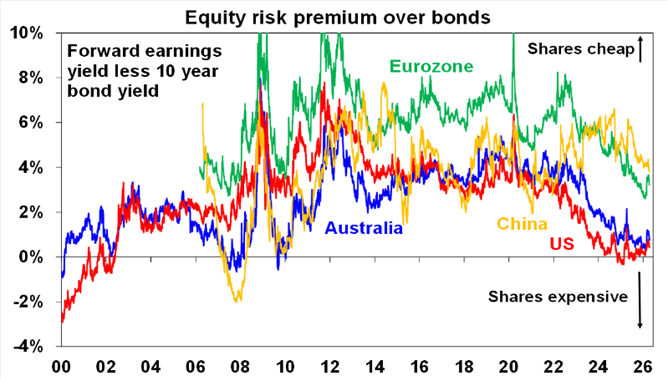
Economic and market volatility becomes a feature, not a bug, which increases risk premium.
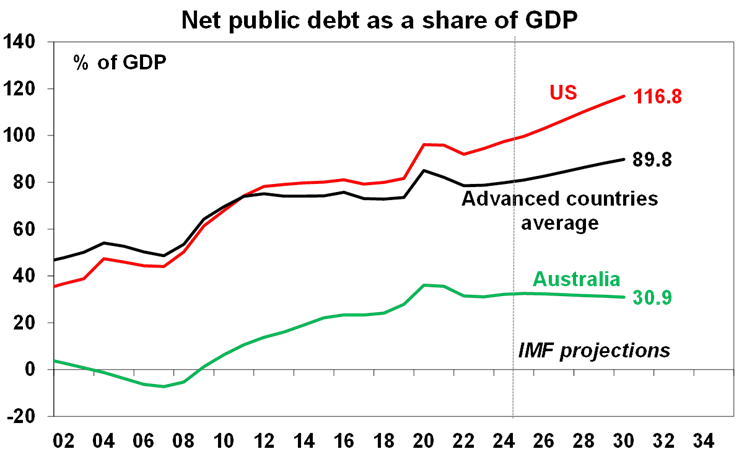
9. Bigger government and rising public debt
Defence, energy security, and cost‑of‑living support together with an ageing population drive higher public spending
Budget deficits and debt levels rise further from already elevated levels